How to Make Money From a Personal Finance Blog
Posted by pauls walkers
Filed in Other 3 views
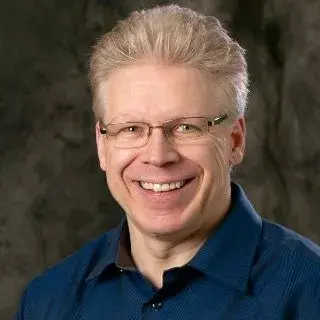
Choosing the right financial planner can be one of the most important decisions in building long-term financial security. With countless financial professionals offering investment advice, retirement strategies, and tax planning services, finding someone who combines experience, knowledge, and a personalized approach can be challenging. This is where an Ed Rempel review becomes particularly interesting. With decades of experience in financial planning and taxation, Ed Rempel has established himself as a recognized name in Canada's financial planning industry.
As a fee-for-service financial planner, tax accountant, and investment strategy expert, Rempel brings a distinctive perspective to personal finance. Through his blog, Unconventional Wisdom, and his extensive financial planning practice, he shares insights intended to help Canadians make more informed decisions about their money. But what makes his approach noteworthy, and why might individuals and families consider exploring his services?
Who Is Ed Rempel?
Ed Rempel is an experienced Canadian financial planner and tax accountant who has dedicated much of his professional career to helping individuals and families improve their financial futures. According to his professional background, he has 28 years of experience as a fee-for-service financial planner and 36 years of experience as a tax accountant.
These combined areas of expertise give him an understanding of how financial decisions influence different aspects of a person's life. Investment performance, taxation, retirement income, and long-term wealth preservation are closely connected. Understanding these relationships can make a significant difference when developing an effective financial strategy.
Over the years, Rempel has built one of Canada's largest financial planning practices and has prepared comprehensive, personalized financial plans for more than 1,000 Canadian families. This experience reflects his involvement in helping clients navigate financial decisions at different stages of life.
Rather than focusing exclusively on investment products, his approach emphasizes broader financial planning and the importance of understanding each client's individual circumstances.
Understanding the Fee-for-Service Financial Planning Model
One of the most interesting aspects of an Ed Rempel review is his fee-for-service business model. Unlike certain traditional financial advisory arrangements that involve commissions from selling investment products, fee-for-service planning generally involves clients paying directly for professional financial advice.
This distinction matters because it changes how financial planning services are structured.
When clients pay for advice separately, they can evaluate the value of the recommendations independently of any investment product being offered. It also encourages a conversation centered on financial goals, planning requirements, and individual circumstances.
For Canadians considering professional financial guidance, this model offers several potential advantages:
-
Greater transparency: Clients can understand what they are paying for and evaluate the services provided.
-
Personalized recommendations: Financial strategies can be developed around individual needs rather than a standard product offering.
-
Comprehensive planning: Advice can address retirement, investments, taxation, and wealth management together.
-
Long-term perspective: The focus can remain on financial objectives instead of short-term product transactions.
However, fee-for-service planning is not automatically the right choice for everyone. Prospective clients should understand the fee structure, services included, and any additional investment management costs before making a commitment.
Unconventional Wisdom: Sharing Financial Knowledge With Canadians
Another important element of Ed Rempel's professional identity is his blog, Unconventional Wisdom. Recognized as the number-one blog in Canada for a financial planner, it provides an opportunity for readers to explore his perspectives on personal finance, investments, taxation, and retirement planning.
Financial information is widely available online, but not all advice is equally useful. Many Canadians encounter conflicting opinions about investing, saving, debt management, and retirement. Consequently, having access to explanations from an experienced financial professional can help readers evaluate different strategies more carefully.
Through Unconventional Wisdom, Rempel shares his opinions, knowledge, and observations about financial topics that affect everyday Canadians.
The blog's unconventional perspective is particularly interesting because financial decisions are rarely as simple as following a universal formula. A strategy that works for one household may be unsuitable for another because of differences in income, expenses, family responsibilities, investment timelines, and tax situations.
Readers can use educational financial content to develop better questions, challenge assumptions, and become more involved in their own financial decisions.
Nevertheless, blog articles should be treated as educational resources rather than individualized financial recommendations. Every investor's circumstances are different.
Experience in Tax Planning and Investment Strategies
Tax planning is an essential part of successful financial management. While many investors concentrate primarily on investment returns, the amount they ultimately retain after taxes can be equally important.
With 36 years of experience as a tax accountant, Rempel brings substantial taxation knowledge to his financial planning work. This combination is particularly valuable because investment decisions can have consequences beyond portfolio performance.
For example, Canadians may need to consider how different registered and non-registered accounts affect their financial plans. Registered Retirement Savings Plans (RRSPs), Tax-Free Savings Accounts (TFSAs), and other investment arrangements have different rules and tax implications.
An effective financial strategy considers these differences while taking into account income, retirement expectations, and future financial needs.
Investment planning also requires careful attention to risk, diversification, time horizons, and personal objectives. Instead of evaluating investments in isolation, comprehensive planning considers how each financial decision contributes to a larger strategy.
Rempel's combined experience in accounting and financial planning provides a foundation for examining these interconnected issues.
Personalized Financial Plans for Canadian Families
A major highlight of this Ed Rempel review is his experience preparing financial plans for more than 1,000 Canadian families.
Every family has different priorities. Some want to retire early, while others are focused on paying off their mortgage, funding their children's education, or building long-term investment portfolios.
A personalized financial plan can help organize these priorities into a practical framework.
Typically, comprehensive financial planning involves examining several important areas:
Retirement planning: Estimating future income requirements and determining how savings and investments can support retirement goals.
Investment strategies: Evaluating risk tolerance, diversification, and investment timelines to develop an appropriate approach.
Tax efficiency: Identifying opportunities to organize finances more effectively while following applicable tax regulations.
Long-term wealth management: Considering how current financial decisions may affect future financial stability and family objectives.
The value of personalization lies in connecting these different elements. Instead of treating financial decisions as separate activities, a comprehensive plan considers how they influence one another.
For families with complicated financial circumstances, this broader perspective may be especially useful.
What Should Potential Clients Consider?
Although Ed Rempel's professional experience is notable, choosing a financial planner requires more than reviewing years in business or professional credentials.
Potential clients should consider whether his planning philosophy aligns with their financial priorities. They should also understand how services are delivered, what the fees cover, and whether ongoing advice is available.
Other important questions include:
-
Does the planner explain recommendations clearly?
-
Are financial strategies tailored to individual circumstances?
-
How are investment risks evaluated?
-
What is included in the financial planning engagement?
-
Are potential conflicts of interest disclosed?
-
Does the planner hold the appropriate professional qualifications and regulatory registrations?
It is also worth discussing expectations before entering a professional relationship. Financial planning is a collaborative process, and successful outcomes depend on clear communication, realistic goals, and regular reviews.
No financial planner can guarantee investment returns or eliminate market risk. A responsible evaluation should therefore focus on the quality of the planning process rather than promises of exceptional performance.
Final Verdict: Is Ed Rempel Worth Exploring?
This Ed Rempel review highlights several aspects that make his professional background interesting to Canadians seeking financial guidance. His 28 years of fee-for-service financial planning experience, 36 years in taxation, and work with more than 1,000 Canadian families demonstrate substantial involvement in the financial planning industry.
His Unconventional Wisdom blog also provides an additional platform for sharing financial knowledge and encouraging readers to think critically about common financial assumptions.
Perhaps the most significant feature of his approach is the combination of tax expertise, investment knowledge, and comprehensive financial planning. These areas are closely connected, and understanding their relationship can help individuals make more informed decisions about their financial futures.
Ultimately, whether Ed Rempel is the right financial planner depends on an individual's needs, expectations, and compatibility with his approach. Prospective clients should review his services, verify relevant credentials, understand the costs, and compare available alternatives before making a decision.
Financial security rarely comes from a single investment or one perfect decision. It develops through consistent planning, informed choices, and the willingness to adapt as circumstances change. As Canadians face evolving economic conditions and increasingly complex retirement challenges, could a more comprehensive and unconventional approach to financial planning help them build a more confident future?